Buy less on purpose. Keep the spending that matters.
You decide, “I’m buying less this month.”
On day three, you skip a shirt. On day six, two home-decor purchases seem harmless because clothing was the category you meant to cut. A stressful evening later in the week ends with delivery.
You may be buying less in one place, but you never decided what low buy meant everywhere else.
A low buy month challenge works better when it is built around rules rather than vague restraint. For 30 days, necessary spending continues, selected discretionary spending remains possible, and the categories that cause trouble get clearer boundaries before temptation appears.
Low-buy works best when the rules remove decisions you keep regretting without removing the spending you genuinely value.
Low-Buy Is Not the Same as No-Buy
A no-buy or no-spend challenge makes the default answer to targeted discretionary purchases “no.” A low-buy month leaves some decisions open, but narrows the conditions for saying yes.
You might allow two restaurant meals, replace shampoo only when another bottle is genuinely needed, cap hobby spending at $50, and pause home decor completely. That is different from trying to spend nothing.
If you want a short experiment where most discretionary purchases stop altogether, a no-spend week challenge is cleaner. A low-buy month is more useful when you want selective limits without treating every enjoyable purchase as a mistake.
Set a clear beginning and end
Use 30 consecutive days, with the start date counted as day 1. That may cross two calendar months. Write both dates down before you start; the rule board below can calculate day 30.
Cover essentials and obligations first, including debt minimums, dependent care, health, safety, and necessary food and transport. If money is already short, a challenge is not a substitute for addressing the shortfall. Do not skip needed care, meals, or bills to keep a streak.
Avoid a discretionary stock-up before day 1. Keep a short list of postponed purchases so you can see whether buying less actually lasted.
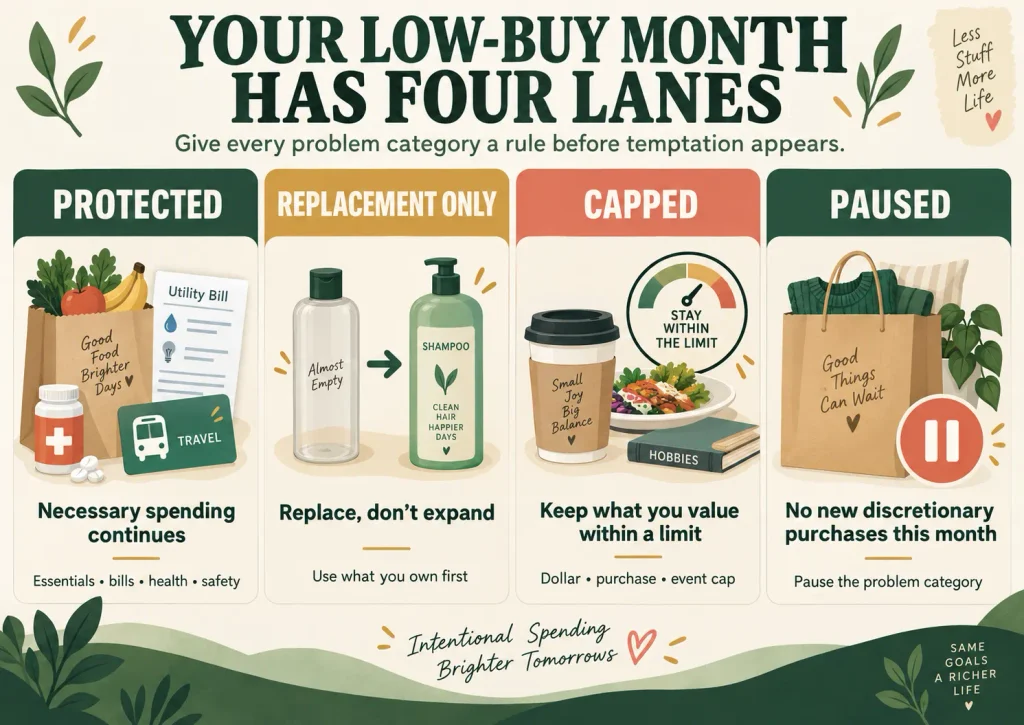
Build the Month Around Four Spending Lanes
“Essential” versus “nonessential” is often too blunt. Put only the categories that need attention into one of four lanes.
Necessary spending continues
Protected covers rent, utilities, necessary groceries, medicine, required transportation, bills, and genuine repairs. Protected does not mean careless spending; it means the challenge does not label normal life as failure.
Replace; do not expand inventory
Replacement Only works when the problem is accumulating more than you use. Toiletries, cleaning supplies, skincare basics, makeup basics, or household consumables may fit here. The rule is simple: replacement is allowed; inventory expansion is paused. If the deeper problem is a backlog of half-used products, the Use It Up Challenge handles that more directly.
Keep valued spending within a limit
Capped categories are things you value but want to contain. A cap can be dollars, purchase count, or event count. “Dining out — two planned meals this month” may work better than banning restaurants if meals with friends are something you genuinely value.
Give a problem category a break
Paused removes a problem category from the decision loop for one month. Clothing, home decor, gadgets, hobby supplies, beauty extras, or marketplace browsing might belong here. The category itself is not universally bad; it is simply where you want no new discretionary purchases this month.
Once you are comfortable buying less, a full no-spend month can be the next step if you want a more structured spending reset.
The useful question is not “Is this purchase morally necessary?” It is:
What rule should control this category this month?
Match the Rule to the Way You Overspend
“Buy less clothing” is hard to enforce because almost every purchase still requires another decision.
If frequent small purchases are the problem, use a count cap:
Maximum two clothing items this month.
If purchase size is the problem, use a dollar cap:
Hobbies get $50 this month.
If duplicate inventory is the problem, use Replacement Only.
If browsing creates purchases you did not plan, combine Paused with a waiting rule.
A strong low-buy rule targets how the overspending happens, not merely the category name.
Also choose one Intentional Yes if that makes the month more sustainable. Perhaps one dinner with friends consistently feels worth the cost while random delivery does not. The lesson is not “restaurants are bad.” It is to protect spending you value and restrict spending that happens automatically.
A low-buy month is not the only option, so it helps to understand how low-buy and no-buy differ before deciding how restrictive your rules should be.
Choose Waiting Rules That Match the Trigger
There is no magic waiting period that works for every purchase.
Use one where urgency is artificial: an online browsing purchase can wait until tomorrow, a grocery-day extra until the next planned shop, and a larger discretionary purchase for several days.
The waiting period should be long enough to interrupt the trigger behind the purchase, but simple enough that you will actually use it.
Low-Buy Month Rule Board
Track only categories that need a rule. Add or remove categories, review activity, and download your board as a CSV. It attempts to save automatically in this browser; a storage message tells you whether that worked.
One category, one clear rule
Start with the categories that cause the most friction. You can use up to 12. This is a manual rule tracker, not a bank-connected spending ledger or a savings calculator.
Choose a start date to show your 30-day period.
Dollar amounts use USD and a decimal point. A blank cap means no limit of that type; a cap of 0 allows none. Blank activity means not recorded. Enter 0 when there has been no activity. Use whole numbers for purchase counts; negative numbers are not accepted. For a capped lane, enter the activity needed to check each cap you set.
The rule board is loading. If it does not appear, use the four-lane rules above on paper.
Browser saving has not been checked yet.
Only named categories are counted. A capped category needs at least one cap. When a dollar cap is set, record current spend; when a count cap is set, record the count used. An incomplete or invalid entry pauses the combined cap-room figure. A count-only cap adds no dollar room.
Unused cap room is neither a spending target nor automatic savings. A reached purchase cap leaves no effective cap room even if some dollars remain. “Categories needing review” includes incomplete entries, limits reached, overspending, unreviewed activity, and recorded rule leaks.
For Replacement Only or Paused, choose an activity review that describes all recorded activity in that category. If some purchases were rule leaks, keep “Rule Leak” and describe the exception in your rule notes. A confirmed replacement or legitimate exception clears that review flag; the board cannot verify receipts for you.
Drafts, including unfinished fields, are saved when browser storage works. Clearing browser data or using another device can remove access. Download a valid board as a backup. The CSV includes rules and activity status, but it is not an import file or a day-by-day calendar.
JavaScript is required for this rule board. Write your dates, lanes, rules, and actual activity on paper instead.
A Simple Review Rhythm for the 30 Days
These are manual checkpoints, not a daily shopping ban. Add them to the calendar you already use.
- Day 1Set your lanes, essential exceptions, start and end dates, and one Intentional Yes. Record the spending you would realistically expect without the challenge.
- Day 7Enter actual purchases and full prices, including fees. Check whether a rule is practical without making daily life harder.
- Day 15Look across categories. Check for replacement purchases, shifted spending, and costs hidden by gift cards or installments.
- Day 30Classify avoided, deferred, and shifted purchases. Decide what to keep, adjust, or drop.
- AfterwardReview the postponed list about two weeks later. Record what you bought after the finish date and revise your conclusion if spending rebounded.
Mid-Month: Check Whether Spending Simply Moved
A low-buy month can look successful while the buying urge changes categories.
Imagine clothing is Paused. By day 15, you have bought no clothes—but home decor, delivery, and hobby spending all increased. The clothing rule worked mechanically, yet your discretionary behavior may not have changed much.
This is category migration. Ask:
Did my spending become more intentional, or did it simply move somewhere with weaker rules?
Then look for rule leaks: purchases that technically fit the wording but defeat its purpose.
“Replacement-only beauty” becomes meaningless if every new item is called a replacement while usable alternatives remain. A $50 hobby cap is not really $50 if gift-card purchases or buy-now-pay-later charges are mentally excluded.
A useful test is:
Would I still consider this purchase consistent with my rule if there were no discount, points, gift card, or clever label involved?
If the same category repeatedly breaks through after stress, boredom, or reward-seeking, the rule may not be the whole problem. The guide to stopping spending money to feel better deals with the emotional trigger rather than the monthly limit.
Unexpected Spending Is Not Automatically Failure
Real life does not obey challenge rules.
The Federal Reserve reported that 59% of U.S. adults experienced at least one type of major unexpected expense during the prior 12 months in its Economic Well-Being of U.S. Households in 2025.
A necessary car repair, medicine, required travel, or replacement for essential broken equipment is not the same as quietly turning a Paused category into a loophole.
Separate a rule exception—spending that genuinely needed to happen—from a rule leak, which is discretionary spending relabeled to escape a restriction you chose.
Do not restart the month because life happened. If you deliberately break a discretionary rule, record what happened, identify the trigger, and continue. One purchase is information; abandoning the rest of the month would turn that one purchase into the entire result.
At Month-End, Separate Avoided, Deferred, and Shifted Spending
A lower spending total can mean several different things.
The purchase stopped mattering and disappeared.
You still intend to buy it later. Keep it on the follow-up list.
One category fell while another rose. Subtract that added cost when assessing the result.
Those outcomes should not all be labeled “savings.”
The same caution applies to caps. If your entertainment limit was $100 and you spent $40, the remaining $60 is unused cap room. It becomes meaningful savings only in the context of what actually happened to your overall money.
A 30-day illustration: a lower total is not all savings
Hypothetical example, not a personal result or typical saving. The reference column is an assumed spending plan without the challenge, not observed receipt data. Prices are illustrative USD totals including applicable taxes and fees. Essential spending stays the same and is outside this comparison.
| Purchase group | Reference plan | Paid in challenge |
|---|---|---|
| Takeout and replacement meals | $72 | $48 |
| Decor purchase abandoned | $45 | $0 |
| Extra hobby spending shifted in | $0 | $20 |
| Clothing purchase postponed | $80 | $0 |
| Comparison total | $197 | $68 |
The food row assumes four $18 takeout meals would have cost $72. During the challenge, two takeout meals cost $36 and two replacement meals cost $6 each: $36 + $12 = $48. In this illustration, the $6 covers ingredients bought and fully used for each replacement meal plus its cooking cost, all paid within the comparison window. Assume no pantry drawdown, extra equipment, unused stock, or waste. If your replacement uses pantry stock or requires larger packs, record cash spent and food used separately; pantry food is not free. Do not count the same replacement food again in a separate grocery-saving category.
The headline gap is $197 − $68 = $129, but $80 is simply a delayed clothing purchase. The remaining illustrative reduction is $24 on meals plus $45 of abandoned decor, minus $20 of extra hobby spending.
This comparison does not prove that your bank balance grew by $49. Check actual cash outlays, bills, replacement purchases, refunds received, and new debt across the same dates. A transfer to savings only moves money you already have; it is not another saving to add to the total.
Use the Carryover Test Instead of Repeating Challenges Forever
At day 30, review each rule individually.
Keep
It reduced automatic spending, clutter, or regret and was easy enough to live with.
Adjust
The idea worked, but the cap, wording, or waiting period needs improvement.
Drop
It created more friction than useful benefit.
Then ask one final question:
Did this rule change the spending itself, or merely move it somewhere else?
The best result is not turning every future month into another challenge. If replacement-only skincare, a next-day waiting rule, or two planned restaurant meals still feels useful after the month ends, it can become one of your regular frugal habits that actually save money.
A low buy month challenge should leave you with fewer automatic spending decisions, not a longer list of restrictions.
Keep the rules that make your spending clearer. Let the rest expire with the month.

Read about Jeffi and Frugenza Living
- Recipe Cost Calculator for Home Cooking - November 10, 2026
- How to Save for a Car Insurance Deductible - November 9, 2026
- How to Rebuild an Emergency Fund After Using It - November 4, 2026